
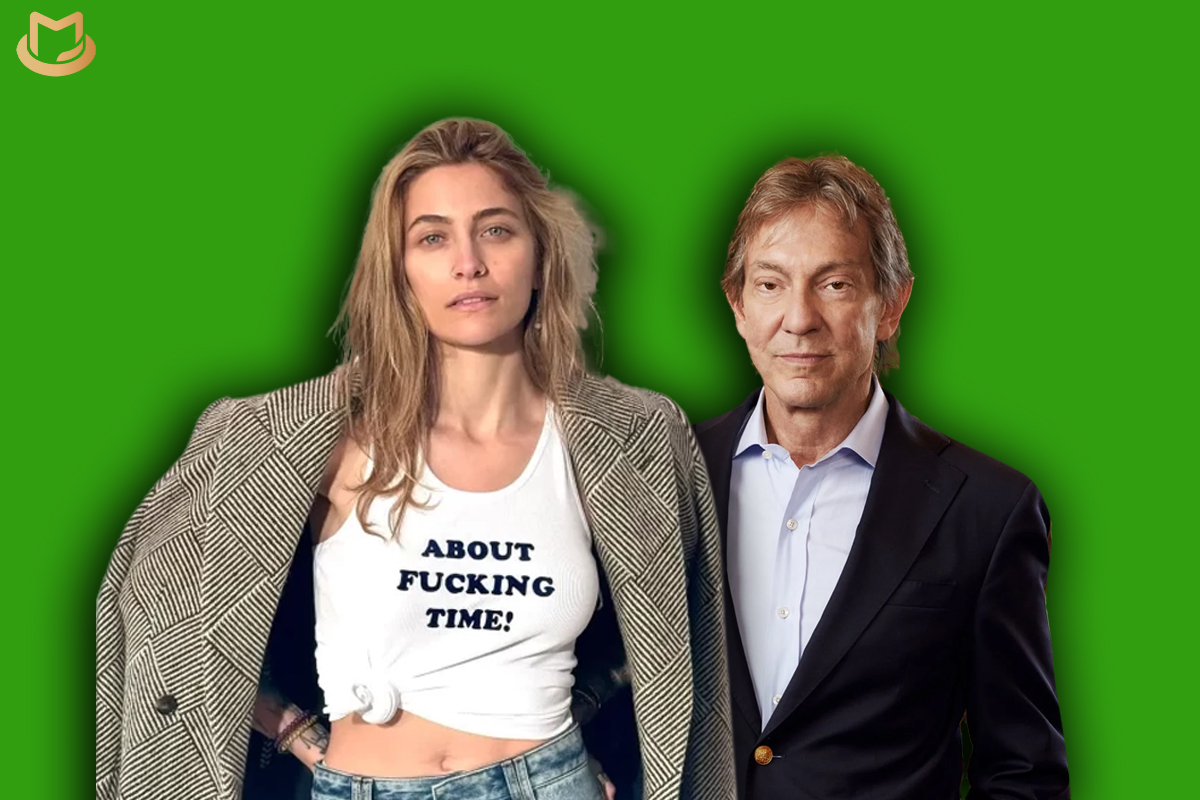
Paris Jackson has filed a new motion in Los Angeles County Superior Court seeking to reduce the compensation associated with the management of her late father Michael Jackson’s estate, raising fresh questions about financial transparency and accountability.
The 28-year-old singer and actress is challenging the arrangements involving John Branca, who has served as an executor of Michael Jackson’s estate since 2009. In her latest filing, Paris asks the court to reduce the compensation rate from 15% to 10% of the estate’s gross entertainment-related income for 2023, 2024 and subsequent years until a complete and accurate 2026 accounting has been filed.
According to the court documents reported by several media outlets, Paris accuses Branca of “persistent incompetence” in relation to the submission of financial statements. She argues that basic accounting responsibilities have not been fulfilled adequately and describes the alleged failures as “intolerable.”
Paris is also asking the court to award her legal fees and costs, arguing that her efforts to address these issues would benefit the estate.
The motion reportedly refers to $109,219,648.27 in proposed compensation involving the estate’s co-executors and a law firm. The precise nature of these payments is central to the disagreement, with Paris questioning the financial arrangements and the estate strongly disputing her position.
The estate’s representatives have rejected the motion, arguing that the executors waived their executor compensation from the beginning and have never received payment in that capacity. They maintain that the payments at issue are separate, court-approved management fees for operating Michael Jackson’s entertainment business.
The estate also disputes the suggestion that the relevant financial statements are overdue, stating that the 2023 and 2024 accountings have already been filed and that the 2025 and 2026 reports are not yet due.
These competing arguments will need to be considered in the legal process. However, Paris’s action brings an important question back into focus: how should the business built around one of the most influential artists in music history be managed, and what level of transparency should beneficiaries expect from those entrusted with protecting his legacy?
This is not the first time Paris has challenged financial decisions involving her father’s estate. Earlier this year, a court ruled that $625,000 in bonus payments previously authorised for outside legal counsel had to be returned to the estate. Paris had also sought reimbursement of accrued interest connected to that dispute.
Her latest motion continues her efforts to scrutinise the financial and administrative arrangements surrounding the estate.
Michael Jackson’s legacy extends far beyond his music. His catalogue, recordings, image and creative work represent an extraordinary cultural and commercial inheritance. Protecting that legacy requires not only successful business management but also clear reporting, responsible decision-making and accountability to those whose interests the estate is meant to serve.
Paris’s challenge should therefore not be dismissed as merely another disagreement involving Michael Jackson’s family. Asking questions about financial management and seeking clear, complete accounting are legitimate parts of ensuring that an estate is properly administered.
The estate, for its part, maintains that its management arrangements are justified and that Paris’s latest motion has no merit. The court will ultimately have to assess the arguments and the relevant documentation.
For Michael Jackson’s fans, the priority remains the protection of his artistic legacy and the fair, transparent management of everything he left behind. Questions surrounding the administration of that legacy deserve serious scrutiny, and the pursuit of accountability should be welcomed rather than automatically portrayed as a personal conflict.
The case is ongoing, and no outcome on Paris’s latest request has been reported.